Sponsored ContentPartner ContentTue 13 Oct 26
Australia’s Housing Challenge Demands Long-Term Capital Partners

Australia’s housing supply challenge is placing new weight on disciplined, specialist capital as developers look for funding partners that can support projects from acquisition through to completion.
The push to deliver 1.2 million new, well-located homes by 2029, and sustained housing demand beyond that deadline, is changing how developers approach funding relationships.
Where a project might once have been financed in stages, more developers are now assessing which capital partners can provide certainty of funding throughout the entire project lifecycle.
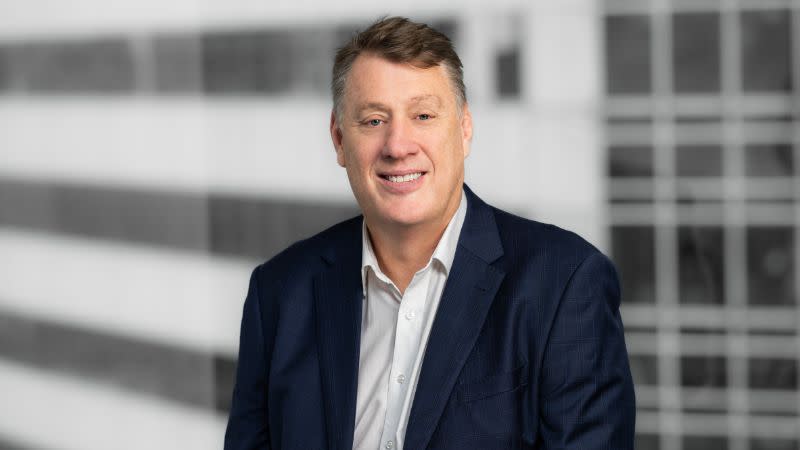
HMC Private Credit head of lending Grant Murphy, who brings more than 35 years’ experience across banking and commercial real estate finance, said funding certainty had become a critical factor for developers under pressure to deliver.
“Viable housing projects require funders that can support them across the full project lifecycle, not just a single point in time,” Murphy said.
“For developers, certainty of funding across the full project lifecycle is critical, from securing and holding land, through construction, and then managing residual stock as settlements are completed.”
Specialist real estate credit with scale
As Australia’s private credit market continues to mature, developers are increasingly seeking lending partners with the balance sheet strength, governance and real estate expertise to support projects across a range of sectors, sizes and stages.
The opportunity extends well beyond simply providing capital.
Developers are looking for lenders that understand the underlying real estate, can assess risk quickly and effectively, and remain aligned throughout the life of a project.
“Experienced private credit lenders can provide a combination of certainty, flexibility and execution capability that is increasingly valued in today’s market,” Murphy said.
According to the Australian Bureau of Statistics, population growth for the year to December 2025 was running at 2.2 per cent in Western Australia and 1.7 per cent in Victoria.
Meanwhile, Queensland’s building approvals rose 4.1 per cent in trend terms in June 2026, alongside a 3.9 per cent rise in New South Wales, pointing to continued momentum across key housing markets.
Specialist credit teams with direct local knowledge and insight can make a real difference to outcomes. HMC Private Credit’s team of more than 70 credit professionals operates from four offices across Melbourne, Sydney, Brisbane and the Gold Coast.
“That local presence supports faster, more informed decisions, while our governance framework ensures speed does not come at the expense of discipline,” Murphy said.
“Our experience spans a broad range of borrowers, asset classes and project types, giving us deep insight into the risks, opportunities and funding structures that support successful delivery.”
Capital backed by discipline and certainty
Backed by ASX-listed parent HMC Capital, HMC Private Credit has deployed more than $8.5 billion in funding and currently manages over $2.2 billion in assets.
That scale provides confidence for borrowers seeking a long-term capital partner capable of supporting well-structured opportunities through varying market conditions.
Approximately 80 per cent of HMC Private Credit’s lending book is in the residential sector, which continues to face pressure from rising construction costs, tighter presale conditions and shifting buyer demand.
“That depth of focus creates a stronger understanding of the projects, borrowers and delivery risks that shape residential development,” Murphy said.
HMC’s dedicated property, legal, risk and credit teams assess feasibility, construction programs, contingency and settlement assumptions from origination through to completion.
“Non-bank lending can offer greater flexibility and responsiveness, but for us every lending decision is underpinned by a rigorous governance and credit framework,” Murphy said.
Funding confidence from approval to completion
Pushing a project through the planning process is only part of the challenge.
Getting construction under way depends on funding structured around the realities of development, including construction timing, cost escalation, presales, equity release and settlement risk.
“Access to the right capital is not just about getting a yes; it is about getting a funding structure that gives the developer confidence to commit and deliver,” Murphy said.
As developers navigate a market where bank appetite has narrowed and delivery timelines have become more important, private credit is playing an increasingly prominent role in funding discussions.
“In today’s market, project fit, certainty of execution and long-term partnership matter as much as the capital itself. Borrowers are seeking lenders that can support them through every stage of a development,” Murphy said.
With capital available backed by a disciplined, proven process and deep real estate expertise, HMC Private Credit positions itself as a long-term funding partner, working alongside borrowers through the opportunities and challenges that arise across the life of a development.
Developers looking to structure funding across the full project cycle can find out more via HMC Private Credit’s borrowing solutions.
The Urban Developer is proud to partner with HMC Private Credit to deliver this article to you. In doing so, we can continue to publish our daily news, information, insights and opinion to you, our valued readers.