IndustryLindsay SaundersWed 14 Oct 26
Trust Tax Bill Sets Up Showdown in Senate for Property Sector

The Federal Government has introduced legislation for a 30 per cent minimum tax on discretionary trusts, setting up a Senate battle over the potential cost to businesses and property investors.
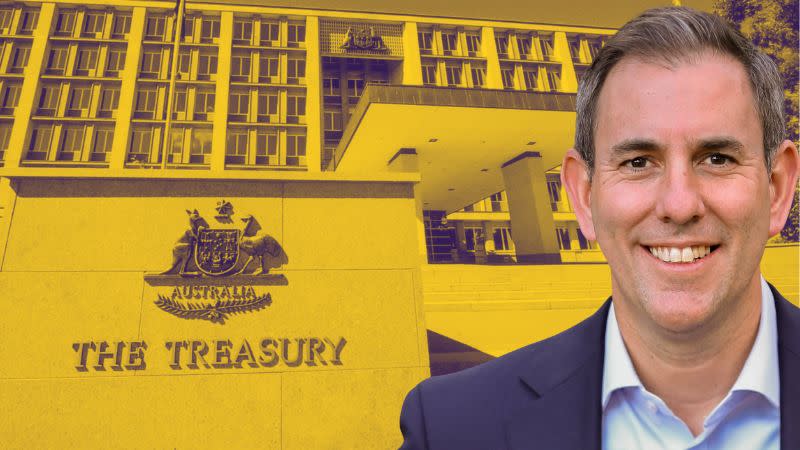
Treasurer Jim Chalmers introduced the bill on Wednesday, October 14, with the proposed tax due to begin on July 1, 2028.
The government expects the reform to raise $4.5 billion over five years, arguing discretionary trusts allow some high-income families to reduce their tax through income splitting.
But the proposal has drawn opposition from business groups, with concerns that restructuring trusts could trigger substantial advisory costs and state-based stamp duty liabilities.
Wilson Asset Management has told media it estimates that restructuring and advice costs could reach between $8 billion and $13.3 billion.
The estimate has become a central point of contention in the debate over the reform.
The Coalition opposes the legislation, while the Greens plan to seek a Senate inquiry, leaving the government needing to negotiate to secure the bill’s passage.
Greens economic justice spokesperson Nick McKim has also raised concerns about exemptions that could allow some trust distributions used to pay private school fees to avoid the minimum tax.
Chalmers has defended exemptions for charities and not-for-profit organisations, saying the government is trying to preserve legitimate uses of trusts while addressing tax advantages unavailable to most wage earners.
Under the proposal, trustees would pay a minimum 30 per cent tax on affected discretionary trust income. The government has also proposed a fixed-distribution election that would allow eligible trusts to nominate beneficiaries and retain an exemption from the minimum tax without restructuring.
The proposed regime would exclude several categories, including charitable trusts, special disability trusts, superannuation funds, deceased estates and certain primary production income.
The government has also proposed expanded rollover relief to help businesses and individuals restructure their affairs ahead of the start date.
For property investors and developers using discretionary trusts to hold assets or operate businesses, the final legislation will determine whether existing arrangements can continue, whether a change in structure is required and what transitional costs may arise.
The bill’s passage and final provisions remain uncertain as the government faces pressure over the scope of exemptions, the cost of compliance and the potential impact on privately owned businesses.